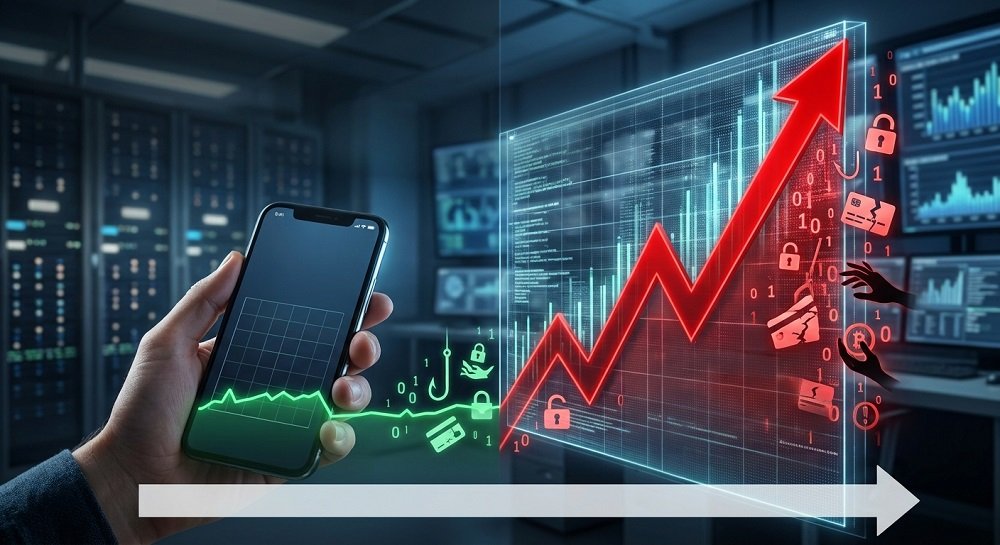
Fraudulent digital banking and money transfer transactions across Africa and the Middle East are projected to reach 175.4 million by 2031, as the growing use of artificial intelligence gives fraudsters new ways to personalise and scale attacks.
The projection is contained in a new report by Juniper Research, which forecasts that fraudulent transactions across digital banking and money transfer services globally will exceed 2.2 billion by 2031, up from 773.7 million recorded in 2025.
The global figure represents an increase of more than 180 percent over the six-year period, according to the research firm.
Juniper attributed the expected rise to the growing use of generative AI and emerging agentic AI by fraudsters, allowing them to develop more personalised scams, automate elements of attacks and adjust their tactics as victims and financial institutions respond.
According to the report, the use of AI is changing the economics of financial fraud by reducing the cost and effort required to produce targeted social engineering attacks at scale.
This is increasing the attractiveness of individual bank customers as targets, with fraud increasingly shifting away from attempts to compromise banking infrastructure towards manipulating customers through authenticated payment journeys.
“Coupled with a reduced cost to commit fraud, AI enables fraudsters to create and adapt attacks faster, while instant payments reduces the window that banks have to identify suspicious behaviour,” said Shane O’Sullivan, author of the report.
O’Sullivan said banks would need to combine behavioural, identity and payment intelligence before transactions are authorised, rather than relying primarily on controls after a payment has been initiated.
Juniper said the growth of instant payments is also creating additional pressure for financial institutions because the speed at which transactions are completed leaves banks with less time to identify suspicious activity and intervene.
The research firm therefore recommended that banks move beyond traditional transaction monitoring and develop a continuous view of customer risk across the payment journey.
It said artificial intelligence could be used to analyse behavioural, identity and payment signals together, allowing institutions to identify changing risk patterns and intervene before fraudulent transactions are authorised.