
Why would a property initially offered for $25 million eventually sell for $9 million?
This is not merely a question about the fortunes of one luxury property in New York. It raises a fundamental question for property owners, investors, developers and valuation professionals: when the eventual sale price is substantially below the original asking price, does that mean the original valuation was wrong?
A property initially offered for $25 million sold for $9 million in the United States. The gold-domed New York City penthouse atop the historic Sohmer Piano Building sold for $9 million through Concierge Auctions after originally being listed for $25 million. The landmark Flatiron District property, characterised by its distinctive gold-leaf dome, was first placed on the market in November 2024 by technology entrepreneur and philanthropist Greg Carr.
After lingering on the real estate market for 530 days and undergoing subsequent price cuts, the final auction bidding closed in July 2026, marking a 64 percent drop from its original asking price. Carr pledged to donate all net proceeds from the sale to the Gorongosa Project, his wildlife and habitat conservation initiative in Mozambique.
For the property owner, the difference between $25 million and $9 million is substantial. For the practising estate surveyor and valuer, however, the more important question is what the two figures actually represent.
A valuation is not necessarily the same thing as the price eventually achieved in a transaction.
The International Valuation Standards Council (IVSC) defines valuation as the act or process of determining an estimate of the value of an asset or liability by applying International Valuation Standards (IVS).
Valuation, according to Richard U. Ratcliff’s pioneering real estate framework, is a prediction of the probable, most likely selling price (market value) of a property through the analysis of human behaviour under market uncertainty.
Ratcliff argued that traditional valuation methods were too rigid and proposed that market value is a probability distribution of potential prices arising from negotiations between buyers and sellers. He identified three distinct capital value figures relevant to decision-making:
- Market Value: The probable selling price of the property in an open market.
- Subjective Value to Owner: The specific utility or worth the property holds for a particular owner.
- Actual Sale Price: The final transaction price achieved through specific negotiations.
This distinction is important. A property owner may attach a very high subjective value to an asset because of its history, location, investment potential or personal significance. A valuer, however, is required to form an evidence-based opinion of market value. The eventual buyer may attach a different value to the same property, depending on financing, intended use, risk appetite and the alternatives available in the market.
The actual transaction price is ultimately determined when a willing buyer and willing seller agree on terms.
The takeaways from Ratcliff’s theory are therefore particularly relevant to the $25 million-to-$9 million example:
- Behavioural prediction: Valuers forecast how market participants will act under uncertain conditions.
- Transaction zones: Prices emerge from a range depending on the bargaining strengths of the parties.
- Probability distribution: Prices form a statistical range rather than a single fixed point.
The International Valuation Standards Council defines market value as the estimated exchange amount for an asset or liability on a valuation date between a willing buyer and a willing seller in an arm’s-length transaction, after proper marketing, and where both parties act knowledgeably, prudently and without compulsion.
This brings us to one of the most important practical aspects of valuation: marketing.
A valuation is made as at a particular valuation date and on specified assumptions. The market, however, continues to move. Buyer preferences change, interest rates change, competing properties enter the market, economic conditions change and sellers’ circumstances may change. Consequently, the price eventually achieved can differ materially from an earlier opinion of value.
When does a property become stale?
A proper marketing period for residential real estate typically ranges from 30 to 45 days, during which peak buyer interest and optimal visibility occur. The precise period, however, varies according to the property, location, market conditions, price segment and nature of the asset.
The practical progression can be considered in phases.
Days 1–14: Peak Interest
Fresh listings generally attract maximum online views and showing requests. This is the period in which the original asking price can be tested against genuine market demand.
Days 15–30: Evaluation Window
Showing traffic and enquiries should be monitored closely. If buyer interest is weak, the seller may need to reconsider the asking price or the property’s presentation.
Days 31–60: Stale Listing Risk
Once a property remains on the market beyond its initial period of exposure, it can begin to lose its “newness premium”. Buyers may start asking why the property has not sold and may interpret prolonged exposure as an indication of pricing or condition problems.
Days 61–90+: Outlier Status
At this stage, the marketing strategy may need to be reviewed. Refreshing the property’s presentation, updating marketing materials, improving staging, temporarily withdrawing the property or changing the pricing strategy may become necessary.
The lesson for property owners is straightforward: an asking price is a marketing decision; a valuation is a professional opinion; and a sale price is the result of an actual transaction. They should not automatically be treated as interchangeable.
The cost of waiting
There is no legal time limit in the United States generally for how long a property can remain listed for sale. However, the longer a property remains on the market, the greater the possibility that buyers will perceive it as stale or overpriced. This is particularly significant for vacant properties.
Vacant properties may face additional insurance requirements, higher insurance costs and increased exposure to vandalism, deterioration and maintenance problems. Sellers also have to consider property taxes, utilities, security and other carrying costs.
In some markets, prolonged vacancy can create additional legal and regulatory obligations. Illinois, for example, does not impose a statewide maximum period for which a vacant property may remain listed for sale, but municipalities and counties can have their own vacant-building and property-registration requirements.
There are therefore financial and legal risks associated with leaving a property vacant for a prolonged period, particularly where the owner is carrying substantial holding costs while waiting for a particular price.
What does the $25m-to-$9m sale really tell us?
The New York transaction provides an important lesson for property owners and valuers.
A 64 percent difference between an initial asking price and the eventual auction price is striking. But the difference, by itself, does not establish that the original valuation was wrong.
The professional question should instead be: what information was available at the valuation date, what changed during the marketing period, how effectively was the property exposed to the market, and what circumstances influenced the eventual transaction?
The distinction is especially important because an asking price may reflect the seller’s expectation rather than an independent professional opinion of market value. Equally, an auction price reflects the circumstances and competitive dynamics of the auction at the time of sale.
The market is not static.
A valuation is an informed estimate at a particular point in time. The eventual sale price is evidence of what a particular buyer was willing and able to pay to a particular seller under particular circumstances.
For practising estate surveyors and valuers, this reinforces the importance of proper market evidence, appropriate valuation methodology, careful analysis of buyer behaviour and clear communication with clients about the distinction between value, price and marketing strategy.
For property owners, the lesson is equally important: an ambitious asking price may not necessarily maximise the eventual return. If the price is materially above what the market is prepared to pay, prolonged exposure can itself become a disadvantage.
The $25 million-to-$9 million transaction therefore offers more than an unusual New York real estate story. It provides a practical reminder that property value is not a number existing independently of the market. It is an informed opinion formed at a particular point in time, while the eventual price emerges from the interaction of buyers, sellers, information, negotiation and market conditions.
That distinction should remain at the centre of every serious conversation about property valuation.
- business a.m. commits to publishing a diversity of views, opinions and comments. It, therefore, welcomes your reaction to this and any of our articles via email: comment@businessamlive.com

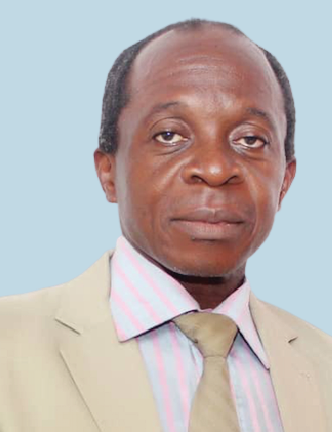
Olufemi Adedamola Oyedele, MPhil. in Construction Management, managing director/CEO, Fame Oyster & Co. Nigeria, is an expert in real estate investment, a registered estate surveyor and valuer, and an experienced construction project manager. He can be reached on +2348137564200 (text only) or femoyede@gmail.com

Reflecting on Geometric Power’s laudation of Abia Government