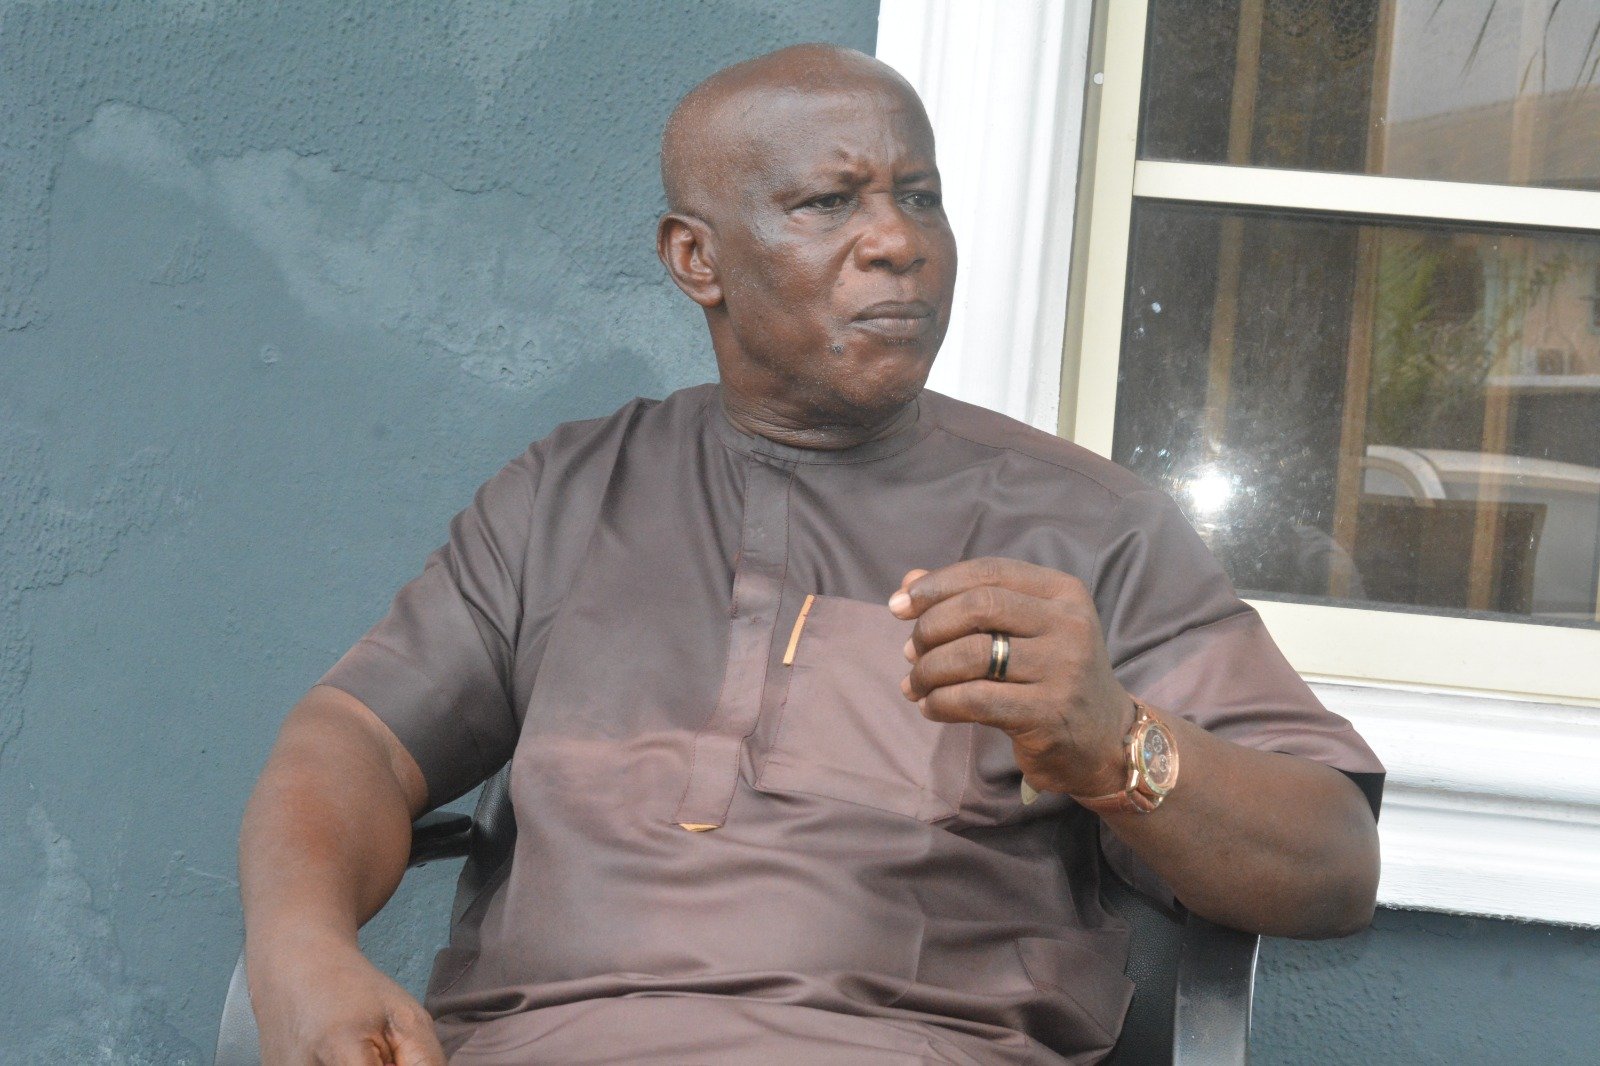
Unlocking the potential of Nigeria’s insurance market will require a fundamental rethink of regulation, distribution and market development. In this exclusive interview with Business A.M.’s PHILLIP ISAKPA, ONOME AMUGE & JOY AGWUNOBI, Lagos-based insurance consultant, law scholar and former managing director of Afribank Insurance Brokers, PASCAL EMEKA EGERUE, discusses the structural challenges constraining the industry, the need for regulatory reforms and opportunities in underserved markets. He also examines how digital platforms, artificial intelligence and innovative insurance products can expand coverage and position the industry for sustainable growth. Excerpts
REGULATION AND THE STRUCTURAL CHALLENGES OF MARKET GROWTH
What are the most significant regulatory changes Nigeria’s insurance industry has witnessed this year, and how are they likely to reshape the competitive landscape for insurers and brokers?
The Nigerian insurance industry has been subject to frequent regulation. We have witnessed more than 10 critical laws, culminating in the present Nigeria Insurance Industry Reform Act (NIIRA). Each law has attempted to address problems that continued to hinder the industry’s growth.
NIIRA is particularly significant because it is an omnibus law that brings together provisions addressing many of these challenges. However, its extensive scope also presents considerable implementation challenges.
Whether it will expand the industry beyond its current position is something only time will tell.
NAICOM is living up to its regulatory responsibility. Even before the recapitalisation exercise ended, we witnessed considerable debate over regulation within the industry. However, I believe we are on the right track.
Despite regulatory efforts to improve claims settlement, public trust and awareness, insurance penetration in Nigeria remains low. What are the underlying structural challenges preventing wider insurance adoption?
It is a recurring question, and one can understand why. Despite all efforts, insurance penetration in Nigeria has not gone beyond 1.5 percent. Even if we are generous and put it at 1.5 percent, that is still very low. In terms of global premium generation, Nigeria is virtually nonexistent. We can hardly be identified on the graphs used to measure global premium pools.
In Africa, we are also underperforming. Smaller countries, including Kenya, are outperforming us, although we must recognise that some of these countries are comparable in size to individual Nigerian states.
Nigeria is a large country, and its insurance market should reflect that potential. There is something structurally wrong with the market. Is it the law, regulation or the practitioners?
With all due respect to the vibrancy created by regulators, I am inclined to believe that our regulatory approach has not been sufficiently directed towards opening up the market. Several laws have been passed, yet we remain largely where we are. Why are regulators not setting clear targets for market growth?
Part of the problem is the assumption that there is so much indiscipline in the market that it must be subjected to extensive regulation. In the process, however, initiatives that could help grow the industry are stifled. Almost every aspect is regulated, including the smallest details, because of the belief that the market will descend into chaos without tight control.
The industry’s structure is also heavily skewed towards urban areas. Rural communities occupy a much larger geographical space, yet significant portions of this market are virtually excluded. They lack insurance practitioners, relevant products and pricing structures that make insurance affordable.
Unlike India, where insurance products are available for practically everything and at different price points, Nigeria often operates a market where people either afford high-premium products or remain excluded altogether.
We need to break down insurance into products that everyone can afford. The principles of insurance remain the same, but practitioners should have the freedom to develop different products within those principles.
We also need to move beyond the argument that low awareness and lack of trust are the principal reasons for poor penetration. Considerable awareness has been created, and the industry is now heavily regulated, with claims settlement obligations. We must therefore look more closely at the products being offered and the structure of distribution.
Another issue is repeated recapitalisation. These exercises may appear to strengthen the industry, but do they necessarily expand the market? Every decade, we lose companies, while others emerge, merge or integrate. Today, companies may report billions of naira in profits, but fewer than 60 insurers are operating. The profitability of individual companies does not, by itself, demonstrate that the market’s fundamentals have improved.
We have also lost an important source of international expertise in reinsurance. When Swiss Re, Munich Re and other international reinsurers operated here, they brought research capabilities and technical knowledge that benefited the wider industry. They were not merely businesses; they were centres of knowledge, with research departments staffed by experts in different fields.
African Reinsurance Corporation makes some effort in this regard, but we need a stronger research culture across the industry.
Microinsurance is another step in the right direction, but practitioners must embrace its proper culture. In the past, insurance representatives visited customers in their homes, initially on horseback and later on Vespas. They understood the communities they served.
If you are insuring vulnerable people, you must meet them at their level. It does not mean senior insurance professionals must downgrade themselves. Rather, we should train people within rural communities who can earn an income from insurance and help expand the industry’s value chain.
We have 774 local government areas. Are we reaching them? Are brokers structuring their operations to serve these communities? The government must also understand that a larger insurance market strengthens the entire financial sector. Insurance companies are major institutional investors and can provide funds for capital formation.
How are digital platforms, artificial intelligence, data analytics and mobile technology changing insurance distribution and risk assessment in Nigeria?
Insurance companies are trying their best. NIIRA also contains provisions encouraging the industry to move in this direction.
Many insurers are embracing digital platforms. Customers can download policies, access interactive applications developed by the Nigerian Insurers Association and individual companies, and purchase insurance from different locations. Risk profiles can also be assessed digitally.
However, adoption is slower than in more advanced markets because of challenges involving education, access to digital resources and the difficulty some customers experience trusting transactions conducted entirely online.
Technology will nevertheless help the industry considerably. It will improve pricing and provide information that can help insurers understand the market.
One of our problems has been the absence of effective big-data analytics. We do not fully understand the extent of our market or even all our competitors. Technology can help us identify the markets we need to serve and develop relevant products.
My concern, however, is that regulation should not stifle innovation. If you have a fire insurance policy, for instance, you can develop numerous categories of products from it, provided you operate within established insurance principles.
Product registration should be as fast as possible. NAICOM is doing well in that regard, but practitioners must also begin thinking beyond the traditional policies they have always offered.
Poor data quality and fragmented information systems have been identified as barriers to artificial intelligence adoption in Africa’s insurance industry. What needs to change?
I would first want to be sure that this was precisely what the African Insurance Organisation said. However, poor data quality and fragmented information systems are reasons why we should adopt digitalisation and AI, not reasons to avoid them.
Digitalisation should not necessarily be capital-intensive. What matters more is expertise, software and specialised human resources. It is largely a question of risk appetite and where companies choose to invest their money.
We should also conduct pilot projects. The insurance industry could select a state, perhaps Ogun or Rivers, and introduce solutions designed to expand insurance coverage. We could then measure penetration and determine whether the approach should be replicated elsewhere.
We must become more practical and proactive. I also believe we have reached a stage where younger people should be allowed to analyse the market and determine its future direction, with experienced professionals providing guidance.
EXPANDING THE MARKET AND UNLOCKING NEW RISKS
How would you describe the depth of Nigeria’s insurance market, and what needs to happen to unlock its potential?
Nigeria has a very large potential market. Our population exceeds 200 million, and we have a vast landmass and sufficient levels of literacy in many areas to support market growth. If we have penetrated less than two percent of the market, it means that approximately 98 percent remains untapped.
We need research and analysis to understand this market better. Technology and artificial intelligence can help identify suitable products, determine appropriate pricing and assess the effectiveness of claims payment systems.
The regulator also has a major responsibility. Any regulator who leaves office without moving the market forward has failed, in my view. If penetration is one percent when a commissioner takes office and remains one percent when that person leaves, what has changed?
We also need to unlock underwriting and broking opportunities, make loss adjusters more agile and strengthen the agency channel.
There are many retired insurance chief executives who could still contribute to the industry, but the current system makes it difficult for experienced professionals to establish brokerage firms or agencies. Why should insurance be different from the legal or accounting professions, where experienced professionals can continue practising independently?
Insurance professionals should be able to offer advisory services independently, even from their homes.
Which sectors or emerging risks offer the greatest opportunities for insurance expansion in Nigeria?
Oil and gas is one area. Much of the sector operates like an underground economy, making it difficult to establish the full extent of its activities. If we improve transparency and open up the sector, there is considerable potential for insurance business.
The solid minerals sector is another opportunity. Regulatory failures and the way mining activities are organised, including gold mining in Zamfara State, mean that these activities are not translating into insurance business as they should.
Housing also requires attention. Many properties, including expensive mansions, are not insured. If accountability improves and people become more conscious of the financial consequences of losses, they may be more willing to insure their assets.
Aviation offers opportunities, although limitations in infrastructure and the high cost of air travel are restricting the expansion of services. Insurers must consider products suited to the market that actually exists.
Kidnapping is another risk that requires attention. However, the response should not simply be to create insurance against kidnapping. We should also examine how technology and security measures can prevent abductions and help secure the release of victims.
Ultimately, we need to examine the country’s different sectors together and address their underlying problems.
When one sector improves, it creates opportunities for others.
We should also understand the limits of compulsory insurance. People are more likely to embrace insurance when they believe in the value of what they are purchasing rather than simply because they are compelled to do so.
Products are what the industry sells. We need to expand their range, redefine them where necessary and make them accessible to the people who need them.
NAICOM’s Insurance Sector Strengthening Programme targets 10 percent insurance penetration by 2031, insurance literacy for 25 million Nigerians and coverage for 250,000 SMEs. How achievable are these targets?
They are achievable if we all commit ourselves to them. They align with the Sustainable Development Goals and the African Union’s Agenda 2063.
The problem is that we have become accustomed to setting targets without doing enough to achieve them. Nigeria failed to achieve its Millennium Development Goals, and many opportunities were lost.
Nevertheless, I believe our fundamentals can support 10 percent insurance penetration by 2031. If you take over a company that has been making losses and manage to make even one naira in profit, you have made progress. Nigeria can also make substantial progress from its current low level of penetration.
To achieve this, NAICOM must avoid micromanaging insurance companies. It should give them room to operate and innovate. Governance is important, but it should become part of the industry’s culture rather than being enforced through excessive policing and paperwork.
Industry associations such as the Nigerian Insurers Association and the Nigerian Council of Registered Insurance Brokers should also play stronger roles in promoting discipline among their members.
We must address practices that undermine the industry. For instance, some people in government engage in insurance transactions and collect commissions without being registered brokers or agents. Despite the regulations, it is not clear who effectively monitors or penalises these activities.
The broader economic environment also matters. When people struggle to afford basic necessities such as food and clothing, insurance becomes a lower priority. Insurers must therefore develop products that are affordable and accessible.
THE FUTURE OF BROKING AND MARKET DEVELOPMENT
As digital distribution expands, how will the role of insurance brokers change, and what must they do to remain competitive?
Digital distribution democratises access to the market, but it also gives those who are already well positioned an advantage. Brokers must embrace technology and develop efficient digital channels for delivering insurance products.
Competition will certainly change. We may reach a point where someone can operate from home and serve a substantial part of the market through digital platforms.
This is a threat to conventionally minded companies, but it does not mean insurance brokers will disappear. Rather, digitalisation could expand the market, allowing proactive brokers to make considerable business opportunities available to themselves.
How should stakeholders measure the success of this year’s insurance reforms over the next two to three years?
The lowest-hanging fruit is insurance penetration. If penetration improves and claims management becomes more efficient, profitability will expand and stakeholders will benefit.
If we move from less than two percent penetration towards 10 percent, other aspects of the industry will also benefit. There will be more money to invest, insurance companies will have greater capacity and the relevance of insurance in the economy will widen.
However, we must ensure that our measurement of penetration is accurate. The information should be obtainable from insurance companies’ records. We cannot continue discussing theoretical figures without reliable data.
Market penetration must be the central measure around which other reforms revolve.
Beyond motor, life and property insurance, which sectors offer the greatest opportunities over the next three to five years?
Life insurance remains a particularly important market. Life funds are generally more stable and less volatile than funds from other classes of insurance. Given Nigeria’s population, properly developed life insurance could generate substantial long-term funds for the industry.
We need products that move beyond the perception that life insurance is exclusively about death. Products should be developed in ways that appeal to people of different religious beliefs while still providing meaningful protection.
Telecommunications is another opportunity. Companies such as MTN generate substantial revenue, and the industry should explore insurance products linked to telecommunications services and applications.
For instance, products could be designed around service interruptions or failed calls, with compensation provided when defined insured events occur. Even small premiums could generate significant revenue when attached to a large volume of transactions.
Agriculture also has enormous potential. However, the sector has not developed to the level it should. If it becomes more mechanised and farming activities expand, opportunities for agricultural insurance will increase considerably.
Unfortunately, insecurity, banditry and terrorism have driven many farmers away from their farms. Some of the structures that previously supported the agricultural sector, including marketing boards, have also not been adequately replaced.
Nigeria must return to productive economic activities. If we move from consumption to production, we will generate more insurable risks and create opportunities for the insurance industry.
REBUILDING THE INDUSTRY’S REACH AND INTERNATIONAL CONNECTIONS
Corporate insurers such as British American Insurance and AIICO appeared to have a stronger market presence in the past. Have corporate insurers become less active, and what factors are responsible?
I do not think insurance companies are entirely responsible. The market has shifted, and insurers have shifted with it. The industry has become more urban-focused, moving away from the kind of market development activities previously undertaken.
Many companies are now more interested in pursuing large contracts worth billions of naira from organisations such as NNPC, rather than collecting smaller premiums from large numbers of people. Yet those small amounts can accumulate into substantial revenue.
We can return to broader market engagement. Nigeria has 774 local government areas, and there are enough people to move around the country, promote insurance and develop products that address local needs.
In my own community organisation, we introduced a life insurance arrangement that provides a benefit of about ₦1 million. When we recently lost a member, the organisation received almost that amount. Without the insurance, we might not even have been able to raise ₦200,000 or ₦300,000 through individual contributions.
This demonstrates what insurance can achieve at community level.
Insurance thrives on large numbers. Some products may appear unprofitable because the number of people purchasing them is insufficient. With a larger customer base, those same products could become viable.
Major insurance companies making substantial profits should dedicate some resources to market development. Such investments may not produce immediate returns, but they can create opportunities for the entire industry.
We should study countries such as India and other Asian economies to understand how they developed their insurance markets. There is substantial business potential at the bottom of the economic pyramid, but tapping into it requires commitment and persistence.
Insurance companies must adopt a longer-term perspective rather than expecting every investment to generate immediate profits.
How do you see the global insurance industry evolving, particularly as international insurers and reinsurers explore opportunities in African markets such as Nigeria?
Globally, despite the risks associated with wars and geopolitical challenges, the insurance market is not doing badly. The industry has developed ways to assess and manage risks, supported by reinsurance products and risk management tools.
International markets also have stronger distribution systems and more developed reinsurance arrangements that enable companies to participate in business and spread risks.
Nigeria previously had a stronger international presence in its insurance market. Modern insurance was introduced by the British, who established agencies that eventually developed into insurance companies.
We later pursued indigenisation and transferred ownership and control to Nigerians. However, after taking control, we began running the market in ways that contributed to its decline.
Insurance is an international business, and premiums and risks are balanced across countries and continents. If international reinsurers are not sufficiently involved in helping us share risks, we lose important opportunities.
Our regulatory framework should accommodate responsible international investment. Foreign companies should be encouraged to invest and contribute expertise, while appropriate safeguards ensure that their activities benefit the local market.
There is a great deal we can learn from international players. We should remain open to that knowledge while putting safeguards in place against unethical practices.
FOUR-YEAR OUTLOOK AND RECOMMENDATIONS
What are your projections for the insurance industry over the next four years, and what are your recommendations?
If the capital we have today is not eroded by currency depreciation, I believe we should be able to achieve at least two percent insurance penetration, maintain strong solvency and invest appropriately in expanding the market.
If the country remains peaceful and the government becomes more deliberate about using borrowed funds to develop infrastructure, economic activities will increase and insurance will benefit.
When roads and railways function effectively, goods move freely and businesses become more productive, the insurance industry will have more opportunities.
We also have more qualified insurance professionals today than we had in the past. The market should therefore be developing rather than retrogressing.
We need peace in the country, the return of industries and an improvement in Nigerians’ per capita income. We also need an efficient taxation system through which revenue can be reinvested in the economy.
Once these conditions are in place, insurance will become a more attractive and accessible product for more Nigerians.
For now, the majority of Nigerians are struggling financially, and insurance may not be among their immediate priorities. However, insurers must also take responsibility by developing products that are affordable, accessible and easy for people to purchase.



The ₦3,000 price of Nigeria’s ‘free’ education