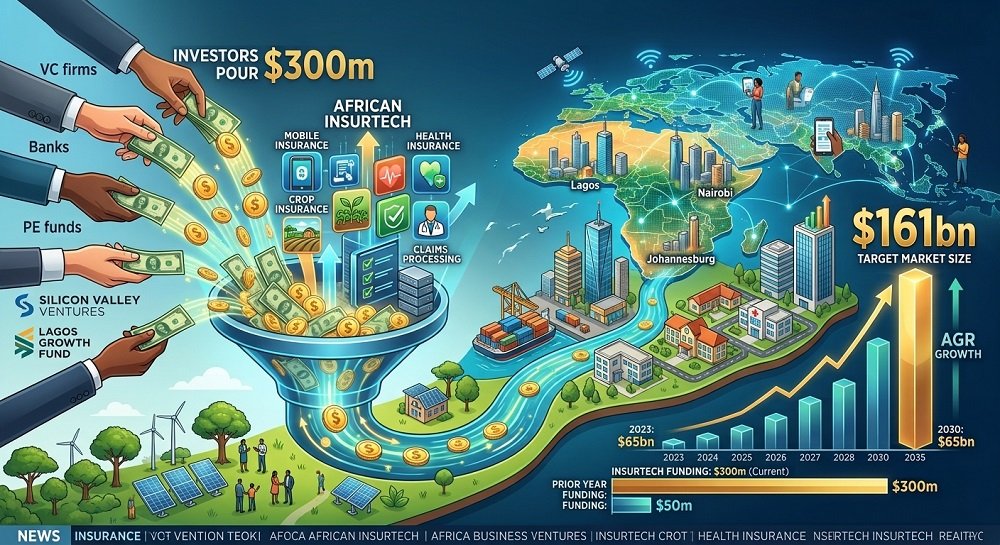
Investors have poured more than $300 million into African insurance technology (insurtech) startups over the past five years as companies seek to expand insurance access across a continent where penetration remains significantly below the global average, according to a new report by AfricInvest.
The report, African Insurtech Landscape 2026, said Africa’s insurance penetration stood at 2.8 per cent in 2024, compared with the global average of 6.5 per cent, highlighting the scale of the market opportunity for technology-driven insurance businesses.
Despite the low level of coverage, the report estimated that Africa’s insurance market was worth $92.9 billion in 2024 and projected that it would grow to $160.9 billion by 2033, attracting startups seeking to make insurance products more accessible, affordable and easier to distribute.
The investment momentum is also gaining pace. Funding for African insurtech startups grew at a compound annual growth rate of 44.1 per cent between 2019 and 2025, reaching a record $80.6 million last year, according to the report.
The findings point to growing investor interest in technology-led approaches to a longstanding problem in Africa’s insurance industry, where limited access, high operating costs and low consumer trust have constrained the uptake of insurance products.
AfricInvest noted that while at least six in 10 Africans have access to a bank or mobile money account, fewer than two in 10 have some form of health insurance, underscoring the disparity between financial inclusion and access to insurance protection.
The report argued that the insurance coverage gap presents both a development challenge and a commercial opportunity for startups using digital platforms to reach consumers who have traditionally been underserved by conventional insurers.
Four markets dominate investment
Although insurtech activity is expanding across the continent, investment remains concentrated in four major markets: South Africa, Kenya, Nigeria and Egypt.
Together, the countries attracted 86 per cent of insurtech investment over the past five years and host some of Africa’s most mature startups, according to AfricInvest.
South Africa and Kenya remain the continent’s most active insurtech markets, supported by established innovation ecosystems, higher insurance adoption and regulatory arrangements that facilitate experimentation and partnerships.
Nigeria and Egypt, meanwhile, are emerging as important centres of activity, with increasing numbers of startups seeking to develop technology-enabled insurance products and distribution models.
The report also identified a broader expansion of early-stage ventures across East, West and North Africa, suggesting that the sector is gradually extending beyond its established investment hubs.
However, the scale of the opportunity varies considerably across markets. Excluding South Africa, Africa’s insurance penetration falls to below one per cent, according to the report.
South Africa accounts for 68 per cent of the continent’s insurance premiums despite representing only 4.1 per cent of its population. Its insurance market is also more heavily weighted towards life insurance, which accounts for 80 per cent of premium volume, compared with 40 per cent across the rest of Africa.
In other African markets, non-life products account for a larger share of premiums, with motor insurance particularly prominent because it is compulsory in many countries.
The disparity illustrates the uneven development of insurance markets across the continent and the challenge facing startups seeking to extend coverage beyond established customer segments.
Technology targets distribution and affordability challenges
AfricInvest identified distribution as the most common entry point for African insurtech startups, largely because it allows businesses to address weaknesses in traditional insurance delivery without necessarily taking on the responsibilities associated with underwriting policies.
Many startups are using digital platforms to connect consumers with insurance providers, simplify enrolment, facilitate premium payments and improve access to insurance products.
Others are moving further into the insurance value chain, developing solutions for product design, claims processing, premium collection and risk assessment.
The report said the growing use of mobile money and digital financial services has created infrastructure that insurtech companies can use to collect premiums and process claims through channels consumers already use.
Digitised financial transactions are also generating customer data that startups can use to assess risk, develop pricing models and serve populations that conventional insurers may struggle to reach profitably.
These approaches are particularly relevant in markets where insurance distribution remains fragmented and the cost of acquiring and servicing customers can make small policies commercially unattractive.
The report identified three interconnected barriers to wider insurance adoption: limited access, low consumer trust and the high cost and risk of serving customers.
According to AfricInvest, these challenges reinforce one another. Limited access restricts the size of insurance risk pools, increasing costs, while expensive products can undermine consumer confidence and discourage further adoption.
Breaking the cycle, it argued, will require changes to product design, distribution and administration rather than relying solely on existing insurance models.
Nigeria introduces new regulatory framework
Regulatory developments are also shaping the sector’s growth, with Nigeria among the markets introducing measures intended to accommodate technology-driven insurance businesses.
The report highlighted two developments in 2025: the National Insurance Commission’s (NAICOM) issuance of dedicated insurtech operating guidelines and the signing of the Nigerian Insurance Industry Reform Act (NIIRA).
According to AfricInvest, the guidelines distinguish between partnering insurtechs, which distribute insurance in collaboration with licensed insurers, and standalone insurtechs, which can underwrite insurance directly under the applicable framework.
The guidelines also provide for digital onboarding and mobile payments, creating a clearer regulatory pathway for technology companies seeking to collaborate with insurers and telecommunications operators.
The report said the framework addresses previous regulatory obstacles to partnerships between insurers and telecommunications companies, which could help expand insurance distribution through established digital channels.
Kenya has also developed mechanisms to support innovation through its BimaLab incubation hub and BimaBox regulatory sandbox, which allow startups to test products under regulatory supervision.
In South Africa, an established insurance regulatory framework and fintech sandbox support innovation, although relatively high capital requirements can make partnerships with existing insurers more practical for startups than obtaining independent underwriting licences.
Egypt is also developing its regulatory environment, with the Financial Regulatory Authority establishing a sandbox for non-banking financial services and approving the establishment of its first licensed microinsurer in December 2025.
AI and embedded insurance shape next phase
Looking ahead, AfricInvest expects the next phase of African insurtech development to depend on the ability of startups to combine technology with more sophisticated products, effective distribution and sustainable business models.
Artificial intelligence could help companies improve risk assessment, refine pricing and automate operational processes. However, the report cautioned that technological capability alone would not determine which businesses succeed.
Instead, startups will need to integrate emerging technologies into products that meet customer needs while keeping distribution and servicing costs low enough to support growth.
Embedded insurance, in which coverage is incorporated into other products and services, is another opportunity identified by the report. Integrating insurance into financial services, mobile money platforms and telecommunications offerings could help companies reach consumers through existing customer relationships.
The report also highlighted opportunities in combining health insurance with wellness services, bundling insurance with other financial products and expanding across national borders.
AfricInvest pointed to India’s insurtech market as a possible reference for Africa’s development. India has more than 150 insurtech startups and $2.7 billion in cumulative funding, according to the report.
Its analysis suggests that African markets are approximately five years behind India in their insurtech development, with the sector progressing from digital distribution towards direct underwriting and, eventually, broader technology platforms.
Transition is still at an early stage for Africa with most activity concentrated on expanding distribution and initial signs of a shift towards underwriting.
The report said the long-term opportunity will depend on whether startups can move beyond making insurance easier to buy and develop commercially sustainable models capable of extending meaningful protection to underserved populations.
While the projected market growth offers considerable potential, closing Africa’s insurance gap will ultimately require businesses to convert investment and technological innovation into products that consumers can afford, understand and trust.





Nigeria must lead more in Africa