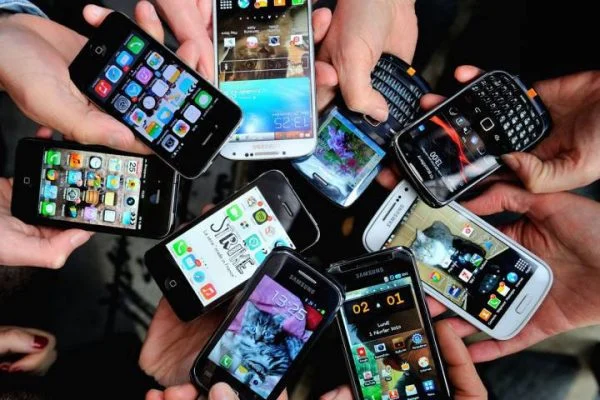
Global smartphone shipments fell by 20 per cent year-on-year in the third quarter of 2026, reaching their lowest level for the period in 14 years, as rising memory costs and supply shortages disrupted production and pushed device prices higher.
Preliminary data from Counterpoint Research’s Market Monitor service showed that shortages of dynamic random-access memory (DRAM) and NAND flash storage increased manufacturing costs and constrained shipments by most original equipment manufacturers (OEMs).
The rising cost of components has also pushed smartphone prices higher, with global retail prices increasing by about 20 per cent so far in 2026, according to the research firm.
The market contraction affected major manufacturers differently, with Samsung retaining the largest share of global shipments at 23 per cent, followed by Apple at 22 per cent. Chinese manufacturers Xiaomi, OPPO and vivo recorded weaker performances as higher production costs put pressure on their shipment volumes.
Shilpi Jain, senior analyst at Counterpoint Research, said the third quarter was the second consecutive quarter in which the smartphone industry had experienced the full impact of the memory shortage.
“The extreme memory shortage is pushing the smartphone market into a more selective phase, reshaping OEM strategies and even consumer behavior,” Jain said.
She said consumers were keeping their existing devices for longer, considering refurbished smartphones and placing greater emphasis on value for money, while manufacturers were adjusting prices, product portfolios and market strategies to protect profitability.
Samsung leads as Apple reaches record Q3 share
Samsung maintained its position as the world’s leading smartphone vendor in the third quarter, although its shipments declined by three per cent year-on-year.
Its market share rose to 23 per cent, representing the largest share gain among major smartphone manufacturers during the period.
Counterpoint Research attributed Samsung’s performance to its stronger position in securing component supplies, demand for premium devices and the early reception of its Galaxy Z Fold8-led foldable smartphone series.
The company’s focus on higher-priced devices supported its performance despite lower shipment volumes, while stable component supplies helped its Galaxy A series maintain its presence in mid-range markets, including emerging economies.
Apple recorded a 22 per cent share of global smartphone shipments, crossing the 20 per cent threshold for the first time in any third quarter, despite a year-on-year decline in shipments.
According to Counterpoint Research, Apple’s lower shipment volume was partly due to a smaller launch-month supply to distribution channels compared with the previous year. The absence of a base iPhone 18 model during the period also contributed to the difference.
However, the iPhone 18 Pro models recorded a stronger launch than their predecessors, particularly in China and India, while continued demand for the iPhone 17 series helped offset the decline.
Apple also increased prices during the quarter, although the impact was limited to the final weeks of the period.
Xiaomi, OPPO and vivo lose ground
Xiaomi’s share of global smartphone shipments stood at 12 per cent in the third quarter, as the company reduced its exposure to lower-priced products and some overseas markets amid rising component costs.
The manufacturer has been tightening shipment plans to avoid selling devices at unprofitable margins while expanding its presence in China’s upper mid-range and premium segments.
Counterpoint Research said Xiaomi’s Xiaomi 18 series and foldable devices received a positive response, while its in-house XRING O3 chipset supported its efforts to differentiate products in the premium market.
OPPO and vivo recorded shipment declines of more than 20 per cent year-on-year, with their market shares falling to nine per cent and eight per cent, respectively.
Both manufacturers increased prices across their entry-level and mid-range product lines in response to higher memory costs.
OPPO also consolidated its product portfolios and operations across OPPO, realme and OnePlus to reduce overlap and improve cost efficiency. The company has prioritised products and markets offering stronger margins.
Vivo, meanwhile, has focused on China and India, strengthening its Y series for budget-conscious consumers while expanding its premium X, V and S series.
However, higher prices have pushed some of its budget models beyond established price ranges, while shortages have further restricted shipments.
Smartphone affordability concerns deepen
The outlook for the global smartphone market remains uncertain, with Counterpoint Research expecting manufacturers to continue prioritising profitability over shipment volumes as memory costs and supply constraints persist.
The firm said smartphone makers were likely to maintain production cuts, streamline product portfolios and focus more heavily on premium devices, while price-sensitive segments faced further pressure from rising retail prices and limited component availability.
The development comes amid wider concerns about the affordability of internet-enabled devices, particularly in low and middle-income countries, where the cost of smartphones remains a significant barrier to digital inclusion.
In September, Business A.M. reported that the Global System for Mobile Communications Association (GSMA) had warned that rising memory and chipset costs, driven partly by the global expansion of artificial intelligence infrastructure, were threatening efforts to make smartphones more affordable for billions of people.
The GSMA report found that an entry-level internet-enabled handset cost the poorest 20 per cent of the population the equivalent of 76 per cent of their average monthly income.
The finding highlights the financial burden facing low-income consumers who need internet-enabled devices to access digital services, including mobile financial services, education, healthcare information and online business opportunities.
With smartphone manufacturers passing higher component costs on to consumers, continued price increases could further complicate efforts to expand smartphone ownership among lower-income populations.
Counterpoint Research said a meaningful recovery in global shipment volumes would depend largely on improvements in memory supply and component pricing, as manufacturers contend with higher production costs and changing consumer purchasing behaviour.