Business A.M
No Result
View All Result
Saturday, October 17, 2026
  • Login
  • Technology
  • Finance
  • Comments
  • Companies
  • Commodities
  • ONLINE & DIGITAL CONTENT PACKAGE
Subscribe
Business A.M
  • Technology
  • Finance
  • Comments
  • Companies
  • Commodities
  • ONLINE & DIGITAL CONTENT PACKAGE
No Result
View All Result
Business A.M
No Result
View All Result
Home Oil and Gas

Oil traders punish OPEC for promising too much

by Admin
May 26, 2017
in Oil and Gas

As OPEC’s latest meeting wrapped up in Vienna on Thursday night, ministers congratulated each other on its rare spirit of amity and consensus. The talks were, without a doubt, a success.

But two hours later, one veteran delegate was staring in despair at the numbers flashing red on his smartphone showing crude down some 5 percent to $51 a barrel.

“That is a disaster,” he said.

While OPEC has worked hard in recent years on improving communication to ensure the right message is delivered to financial markets, Thursday’s experience showed the 14-member group and its non-OPEC allies still have a long way to go.

The problem was not what was delivered, but what appeared to have been promised beforehand, industry analysts said.

OPEC agreed on Thursday to extend its existing production cuts by nine months – more than the initially suggested six months – in tandem with non-OPEC producers, including Russia.

But hints from the group that it could deepen supply cuts, extend them by as long as 12 months, curtail exports and tell the market how exactly it would terminate supply curbs in 2018 had raised market expectations much higher.

“OPEC oversold the meeting to the market way too early,” Amrita Sen, from the consultancy Energy Aspects, told Reuters in Vienna.

The market reaction was all the more disappointing given that from OPEC’s perspective, the meeting went very well.
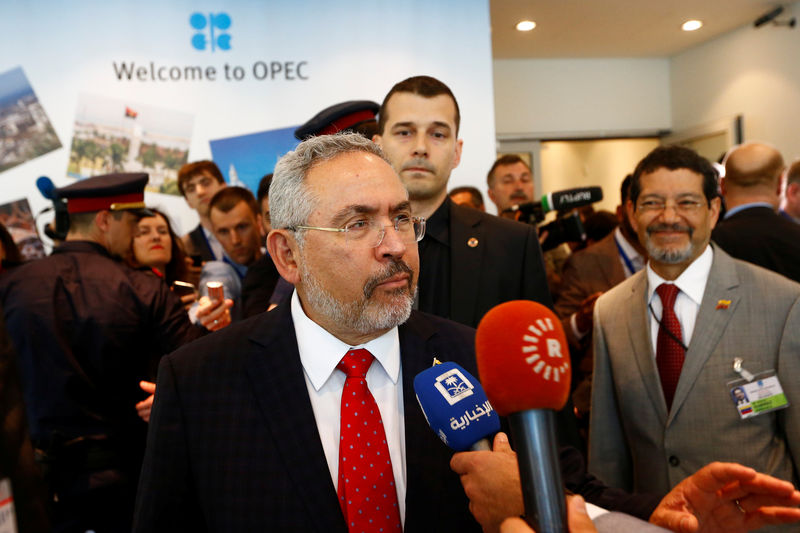
Image result for Amrita Sen, from the consultancy Energy Aspects, told Reuters in Vienna.
Venezuela’s Oil Minister Martinez talks to journalists after a meeting in Vienna

“I have been in OPEC close to 20 years. It’s the first time that I witness 100 percent compliance (with cuts) from OPEC and close to 100 percent from non-OPEC,” Iranian Oil Minister Bijan Zanganeh told Reuters afterward.

OPEC’s No.3 producer, Iran has repeatedly clashed in past meetings with OPEC’s de-facto leader, its political arch-rival Saudi Arabia.

Russia, which effectively is fighting a proxy war with Saudi Arabia in Syria, said on Thursday its energy cooperation with Riyadh would last well into the future.

In its statement, OPEC said it could extend curbs further or cut more.

Normally, all this would be more than enough to trigger a bull rally.

“It’s strange. I don’t know why (the market crashed)” Zanganeh said.

Whatever it takes

OPEC and non-OPEC oil producers first agreed to cut output in December 2016 – the first joint deal in 15 years – and said the curbs could be extended by a further six months.

The extraordinary move was aimed at battling a global glut of crude that halved prices from 2014, forcing Russia and Saudi Arabia to tighten their belts and leading to unrest in Venezuela and Nigeria.

The cuts helped push oil prices back above $50 per barrel but also spurred growth in the U.S. shale industry, which does not participate in the output deal. That slowed a rebalancing of supply and demand, with global inventories still near record highs.

As the price fell back towards $47 in early May, near a six-month low, Saudi Energy Minister Khalid al-Falih said OPEC would do “whatever it takes” to rebalance the market, including a longer extension for the output cuts.

“If you declare nine months in advance, people are bound to expect more,” Sen said. Russia also added to the expectations by saying this week that cuts could be prolonged by 12 months.

The market was also disappointed OPEC did not mention its previously stated plan to bring stocks down from a record high of 3 billion barrels to their five-year average of 2.7 billion, said Olivier Jakob from the Petromatrix consultancy.

“The December meeting was a breakthrough,” he said. “The meeting yesterday gives us, however, a feeling that OPEC is fatigued by the lack of results so far and does not have a consensus anymore to have the five-year average in stocks as a policy target.”

The fact that Iran, Libya and Nigeria remain exempt from cuts suggested OPEC was not yet ready to take additional measures, Jakob added.

Dave Pursell, managing director at Tudor, Pickering, Holt & Co, a Houston-based bank working with U.S. shale producers, predicted markets would rebalance within six months.

“The market was hoping for deeper cuts,” he said. “But I do think oil prices, three months from now, will be higher than they are now.”


Admin
Admin
Previous Post

Nigeria oil governance bill aims to split NNPC

Next Post

OPEC ponders how to co-exist with U.S. shale oil

Next Post

OPEC ponders how to co-exist with U.S. shale oil

  • Trending
  • Comments
  • Latest

How UNESCO got it wrong in Africa

May 30, 2017

CBN to issue N1.5bn loan for youth led agric expansion in Plateau

July 29, 2025
MMA2 enters new commercial era after 20-year concession dispute

MMA2 enters new commercial era after 20-year concession dispute

August 28, 2026
NGX taps tech advancements to drive N4.63tr capital growth in H1

Insurance-fuelled rally pushes NGX to record high

August 8, 2025

6 MLB teams that could use upgrades at the trade deadline

Top NFL Draft picks react to their Madden NFL 16 ratings

Paul Pierce said there was ‘no way’ he could play for Lakers

Arian Foster agrees to buy books for a fan after he asked on Twitter

Rivers, China's CNCECC sign deal for $3.5bn methanol, fertiliser plant

Rivers, China’s CNCECC sign deal for $3.5bn methanol, fertiliser plant

October 17, 2026
Methane rules spread across 67% of global production as Nigeria faces compliance test 

Methane rules spread across 67% of global production as Nigeria faces compliance test 

October 17, 2026
Onafriq, a pan-African payments company, is set to discontinue its Baxi agent banking business in Nigeria after five years, citing naira depreciation, rising operating costs and intensifying competition that have weakened the segment’s profitability. The planned shutdown will affect the agent banking operations conducted through Baxi under Onafriq Nigeria Payments Limited. However, the decision does not signal the company’s withdrawal from Nigeria, as it intends to retain its cross-border payments network and card issuing services in the country. In a statement, Onafriq said changes in Nigeria’s operating environment since 2024 had significantly altered the economics of its offline agent banking business, making the existing model unsustainable. The move marks a strategic shift for the company, which entered Nigeria’s agent banking market to expand access to financial services through a network of agents providing transaction services outside traditional bank branches. Onafriq attributed the decision to a combination of macroeconomic pressures and structural changes in the country’s payments industry. According to the company, naira depreciation and inflation have affected transaction volumes, increased operating expenses and undermined the sustainability of its agent banking operations. The growing adoption of instant account-to-account transfers has also changed the mix of transactions handled by agents, while heightened competition among payment service providers has put further pressure on margins. These developments have made it increasingly difficult for the business to remain viable under its existing operating structure, prompting the company to reassess its long-term strategy. Dare Okoudjou, founder and chief executive officer of Onafriq, said the decision to close the business was difficult, particularly given the efforts of employees, agents and business partners who helped build the Baxi network. “We entered Nigeria with conviction and commitment, but did not achieve the outcome we set out for. Closing this business was a difficult decision to arrive at, one that affects colleagues, agents, and business partners across Nigeria who poured their hearts and soul into building out the Baxi network,” Okoudjou said. Despite the closure, he reaffirmed the company’s commitment to the Nigerian market, noting that the group would continue to serve customers through its payments network and card issuing operations. Onafriq entered Nigeria’s agent banking market in 2021 through the acquisition of Baxi, also known as Capricorn Digital Limited. The company said it continued investing in the business through 2023, with efforts focused on expanding and strengthening its agent network. However, a subsequent review of the business’s long-term prospects and financial sustainability led to the decision to wind down the operation. As part of the transition, Onafriq said agents onboarded through the Baxi platform had been moved to another principal bank, a step intended to facilitate continuity for the affected agents. The company has also directed agents to transfer their funds to their preferred principal bank within 30 days, adding that its teams would provide support throughout the transition process. Employees whose roles are linked to the agent banking business will also be consulted and supported during the wind-down, with Onafriq pledging to treat affected workers fairly.

Onafriq winds down Baxi as Nigeria’s agent banking economics worsen

October 17, 2026
LCFE links petroleum trading to capital market in pricing transparency drive

LCFE links petroleum trading to capital market in pricing transparency drive

October 17, 2026

Popular News

  • How UNESCO got it wrong in Africa

    0 shares
    Share 0 Tweet 0
  • CBN to issue N1.5bn loan for youth led agric expansion in Plateau

    0 shares
    Share 0 Tweet 0
  • MMA2 enters new commercial era after 20-year concession dispute

    0 shares
    Share 0 Tweet 0
  • Insurance-fuelled rally pushes NGX to record high

    0 shares
    Share 0 Tweet 0
  • Glo, Dangote, Airtel, 7 others prequalified to bid for 9Mobile acquisition

    0 shares
    Share 0 Tweet 0
Currently Playing

CNN on Nigeria Aviation

CNN on Nigeria Aviation

Business AM TV

Edeme Kelikume Interview With Business AM TV

Business AM TV

Business A M 2021 Mutual Funds Outlook And Award Promo Video

Business AM TV

Recent News

Rivers, China's CNCECC sign deal for $3.5bn methanol, fertiliser plant

Rivers, China’s CNCECC sign deal for $3.5bn methanol, fertiliser plant

October 17, 2026
Methane rules spread across 67% of global production as Nigeria faces compliance test 

Methane rules spread across 67% of global production as Nigeria faces compliance test 

October 17, 2026

Categories

  • Frontpage
  • Analyst Insight
  • Business AM TV
  • Comments
  • Commodities
  • Finance
  • Markets
  • Technology
  • The Business Traveller & Hospitality
  • World Business & Economy

Site Navigation

  • Home
  • About Us
  • Contact Us
  • Privacy & Policy
Business A.M

BusinessAMLive (businessamlive.com) is a leading online business news and information platform focused on providing timely, insightful and comprehensive coverage of economic, financial, and business developments in Nigeria, Africa and around the world.

© 2026 Business A.M

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Technology
  • Finance
  • Comments
  • Companies
  • Commodities
  • ONLINE & DIGITAL CONTENT PACKAGE

© 2026 Business A.M