By Godsreal Ojinaka, CEO, Zacuten Technologies
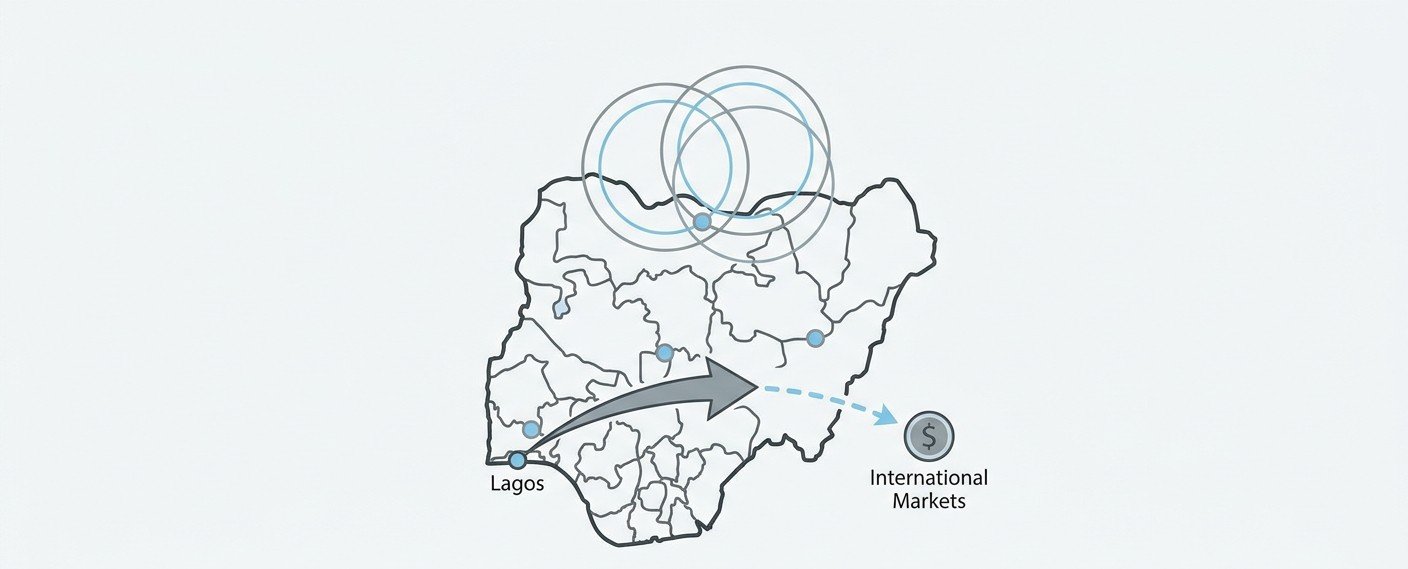
The promise of Africa’s digital economy is built on movement: the movement of money, goods, services, talent and ideas across borders. Nigerian businesses are increasingly engaging with international partners, while fintechs and digital payment platforms are making cross-border commerce easier and faster. But there is a difficult question we must confront alongside this progress: what happens when something goes wrong and millions of dollars have already crossed borders before anyone can intervene?
I am asking this question not as an observer, but as a business owner who has experienced the consequences firsthand. In 2026, Zacuten Technologies entered into a cross-border transaction valued at approximately $13.07 million involving Plaude Technologies Limited and Plaude Inc. Approximately $8.95 million was transferred, while more than $4 million remains outstanding.. Plaude has attributed the failure to complete settlement to banking restrictions, enhanced due diligence, payment-corridor difficulties and other operational challenges. We dispute those explanations and continue to seek a full accounting and settlement of the outstanding amount.
What happened next is what transformed this from a difficult commercial transaction into a much bigger concern for me. At different points in the transaction, Zacuten received financial documentation that was presented to us as evidence that funds were available. One of the documents was a Banc of California cashier’s cheque numbered 1874649, dated March 6, 2026, and made payable to Plaude Inc. for $2,780,208. We subsequently sought to independently verify the instrument with a bank representative and raised serious concerns about its legitimacy.
From our perspective, receiving what we understood to be evidence of available funds, only to later question the authenticity of that documentation, fundamentally changed the nature of the situation. A financial document is not the same thing as available money. A promise to pay is not payment. And a payment instrument that has not been independently verified should never be treated as proof that funds exist.
This experience has forced me to think more deeply about the vulnerabilities that arise when millions of dollars move across borders. When a transaction involves multiple companies, banks and jurisdictions, accountability can become fragmented. One institution may have information about the originating transaction. Another may hold information about the receiving account. A different jurisdiction may have authority over the company or individual involved. By the time a business discovers that something may have gone seriously wrong, the funds may have moved through several financial channels, and recovering them can become significantly more complicated.
That complexity does not only create a challenge for law enforcement. It creates an enormous burden for legitimate businesses. Our experience has changed the way I think about due diligence. Before a company commits millions of dollars to a cross-border transaction, it should be asking much more than whether its counterparty appears legitimate. What is the counterparty’s actual financial capacity? Where are the funds coming from? Can the funds be independently verified? Are the banking arrangements consistent with the transaction? Who ultimately owns and controls the companies involved? Are there existing disputes or unresolved obligations? Can the counterparty actually execute a transaction of the size being proposed? And perhaps most importantly, can every material representation being made during the transaction be independently verified?
At Zacuten, these questions became painfully real after we had already committed substantial funds. We now believe that financial capacity, source and availability of funds, payment instruments, banking arrangements, corporate ownership structures, transaction history and the ability to execute significant cross-border transactions should all be subject to enhanced due diligence before substantial sums are transferred. This is not excessive caution. It is the minimum standard that a global digital economy should demand.
There is also a responsibility that goes beyond individual companies. Banks and fintechs need stronger transaction-monitoring capabilities. Financial institutions should be able to identify unusual transaction patterns, inconsistencies in documentation and activities that warrant enhanced scrutiny. Law enforcement agencies need specialised financial intelligence capabilities and technology that can trace complex transactions across jurisdictions. Regulators need mechanisms that allow relevant information to move between institutions more quickly, while maintaining appropriate safeguards for privacy, confidentiality and due process.
Money can move extremely quickly. If a suspicious transaction can cross multiple financial systems in hours, investigations cannot depend entirely on processes that take weeks or months to establish what happened. The objective should not simply be to investigate financial crime after the fact. It should be to identify risks early enough to preserve evidence, trace funds, identify the relevant counterparties and, where legally possible, prevent further dissipation of assets.
As we sought answers about our own transaction, we also became aware of other allegations and disputes involving Plaude and individuals associated with the company. Some of these claims remain subject to verification and legal process and should therefore be treated accordingly. Separately, the Nigeria Police Special Fraud Unit announced in May 2026 that it had secured a Federal High Court forfeiture order involving accounts and assets linked to Plaude Technologies Limited, Omberra Commodities Limited and individuals named in its investigation. The SFU said the investigation involved allegations concerning approximately ₦8.585 billion, including allegations of fraudulent conversion, obtaining money by false pretence, stealing and money laundering. The investigation and allegations remain subject to the appropriate legal process.
I make this distinction deliberately. Businesses that believe they have been defrauded deserve to be heard and protected. But allegations must still be tested through evidence and due process. Financial-crime enforcement is strongest when it is based on facts that can withstand scrutiny. Our own position is straightforward: we are owed more than $4 million, and we are seeking to recover it.
One of the most frustrating realities of cross-border financial disputes is that knowing you have suffered a loss does not necessarily tell you how to recover it. Which authority should you approach? Which jurisdiction has responsibility? How do you preserve the relevant financial records? How do you trace funds that may have moved through multiple accounts? How do you coordinate information between Nigerian authorities, foreign regulators, banks and other institutions? These questions need clearer answers.
Nigeria’s financial ecosystem needs stronger mechanisms through which businesses that suspect financial crime can report incidents, preserve evidence, access appropriate financial-intelligence channels and understand the process for pursuing recovery. Legal action will always have a role, but victims should not have to navigate an opaque maze simply to understand where their money went and which institution can help them pursue it.
There is a tendency to discuss financial infrastructure in terms of payment rails, APIs, wallets and settlement systems. But trust is also infrastructure. If Nigeria wants to build a globally competitive digital economy, international businesses must have confidence that transactions can be conducted securely and that there are credible mechanisms for responding when they go wrong. The question international businesses will ask is not only whether Nigeria can move money quickly. They will also ask whether the system can follow the money when something goes wrong.
My experience with Zacuten has reinforced this for me. We entered a transaction involving millions of dollars with the expectation that the parties involved had the capacity and intention to complete their obligations. We transferred substantial funds. We subsequently encountered an outstanding balance of more than $4 million, prolonged delays and financial documentation that we say raised serious questions about the availability and legitimacy of funds, including the cashier’s cheque we received and later sought to verify.
Whatever the eventual outcome of our dispute, there is a broader lesson that Nigeria should not ignore. Nigeria cannot build a globally competitive digital economy while allowing unresolved cross-border financial disputes to erode confidence in the system. We should not respond to these risks by slowing innovation or discouraging international commerce. We should respond by strengthening the infrastructure around it: better transaction monitoring, stronger counterparty due diligence, faster financial-intelligence sharing, specialised investigative capabilities and clearer recovery mechanisms for legitimate victims.
The more money that moves across borders, the more sophisticated our ability to protect that money must become. For companies like mine, this is not an abstract policy discussion. It is the difference between conducting business with confidence and spending years trying to recover funds that should never have become untraceable or disputed in the first place. Africa’s digital economy is moving forward. Our financial-crime response must move just as quickly.