-
Dollar, inflation squeeze looms for Africa
-
Nigeria oil cushioning could temper effect
-
Higher global rates could raise cost of capital
-
Global cost of money in complicated phase
The US Fed and the UK’s BoE rate decisions have set the stage for fresh dollar and inflation pressures across Africa, with Nigeria among the economies most exposed to shifting global financial conditions.
The US Federal Reserve has resumed raising interest rates, while the Bank of England has chosen to hold, creating a fresh divergence among major central banks at a time when energy prices, geopolitical tensions and inflation are complicating the outlook for the world economy.
For Africa, the significance of the latest decisions lies less in the 25-basis-point move in Washington or the decision to pause in London than in what they could mean for the flow and price of global capital.
It matters for economies, like Nigeria’s, already grappling with inflation, currency stability, debt-servicing costs and the need to attract investment.
Nigeria sits directly within this transmission channel.
The Federal Reserve raised its benchmark rate by 25 basis points to a range of 3.75 to 4 percent on Wednesday, its first increase since 2023. The Bank of England, hours later, held the Bank Rate at 3.75 percent in a 6-3 vote, with three policymakers favouring an increase.
The two decisions have produced an increasingly fragmented global monetary picture.
Nigel Green, chief executive officer of deVere Group, one of the world’s largest independent financial advisory organisations, sees the Fed’s move as the beginning of another tightening phase.
“A quarter point today [Wednesday] was the easy part. The harder question is what comes after it, and the honest answer is more tightening, not less,” Green said, predicting another Fed increase in December.
That December call remains a forecast, not a commitment by the Federal Reserve. But it highlights the question now confronting investors: what happens to emerging-market currencies, bonds and businesses if US rates remain higher for longer?
The dollar gets the first vote
The first transmission channel is the dollar. Higher US interest rates can increase the relative attraction of dollar-denominated assets, particularly when investors begin to reassess expectations for the duration of the US tightening cycle.
A stronger dollar can then increase the local-currency cost of servicing dollar-denominated debt and raise the return investors demand for holding emerging-market assets.
The effect is not automatic, nor is it uniform across Africa.
Oil exporters can benefit from higher crude receipts. Energy-importing economies face a more direct increase in fuel and transport costs. Countries with significant foreign-currency liabilities can see their debt burden rise in domestic-currency terms.
The common factor is that the Fed influences financial conditions well beyond the United States.
For African markets, the question is therefore not simply whether Washington raises rates again, but how investors compare African assets with the return available from dollar assets.
Nigeria’s oil advantage comes with a catch
Nigeria enters this new global rate environment from a stronger external position than it occupied during some of its previous periods of intense currency pressure.
External reserves have risen above $54 billion, while the naira has shown greater stability. Inflation has also been moderating, with headline inflation easing to 15.39 percent in August from 15.43 percent in July, according to the National Bureau of Statistics.
Those developments provide a degree of protection. But they do not insulate Nigeria from the global dollar cycle.
Indeed, the country’s most important external cushion, crude oil, is also a source of vulnerability.
If geopolitical tensions keep oil prices elevated, Nigeria can benefit from higher export earnings and stronger foreign-exchange inflows. That can support reserves and improve the country’s external position.
But the same oil shock can keep global inflation elevated, encourage major central banks to maintain tighter monetary policies and increase the cost of capital for emerging economies.
Nigeria could therefore receive more dollars from oil while operating in a world where those dollars have become more expensive to borrow.
That distinction will increasingly matter to businesses.
The cost of capital is the real story
For Nigerian companies, the Fed’s decision is unlikely to arrive as a line item labelled “Federal Reserve rate”.
It will show up through borrowing costs, refinancing decisions, exchange rates, imported inputs and investor return requirements.
A manufacturer importing machinery, an airline buying fuel, a bank managing foreign-currency obligations or a company refinancing dollar debt can all be affected by movements in the dollar and global interest rates.
The government faces the same arithmetic. When US Treasury yields rise, emerging-market sovereign borrowers must consider whether they can continue accessing international capital at acceptable rates.
That makes the bond market another important transmission channel.
Green has specifically warned investors about duration, arguing that holders of long-dated bonds bought when yields were lower could suffer further losses if rates continue to rise.
The mechanics are straightforward: when market yields rise, the prices of existing fixed-rate bonds generally fall.
For Africa, however, the issue goes beyond mark-to-market losses.
Higher global yields can influence the return investors demand from African sovereign debt, raising the potential cost of funding for governments and companies.
For Nigeria, that global pressure arrives alongside a domestic financial system still adjusting to high interest rates and tight liquidity conditions.
The BoE’s pause exposes the other side of the problem
If the Fed’s decision highlights renewed tightening, the Bank of England’s hold exposes another difficulty confronting central banks: what to do when inflation is being driven partly by forces they cannot directly control.
UK inflation climbed to 3.1 percent in August, above the Bank’s two percent target.
Green described the BoE’s decision as a risk that Britain could fall behind the inflation curve, arguing that the central bank was choosing “stillness while inflation runs hot.”
That is Green’s interpretation, rather than the Bank’s own characterisation.
The Bank’s decision reflects a more complicated calculation. Its policymakers are weighing persistent inflation against the economic damage that could result from tightening monetary policy into an energy-driven shock.
That dilemma is relevant to Africa. Many African central banks face a similar problem, although often with less room for manoeuvre.
They cannot control global oil prices, shipping costs or geopolitical shocks. What they can do is try to prevent an external price shock from becoming embedded in domestic inflation expectations.
The policy challenge is particularly acute where exchange-rate movements quickly feed into the cost of food, fuel, machinery and other imported goods.
Africa faces an uneven global shock
The latest decisions will not affect every African economy in the same way.
For oil exporters such as Nigeria and Angola, higher crude prices could improve export earnings and fiscal revenues.
For net energy importers, the same shock could worsen inflation and external balances.
For countries with substantial dollar-denominated debt, a stronger US currency can increase debt-service costs.
And for economies dependent on foreign portfolio investment, higher US yields can change the relative attractiveness of local assets.
This makes domestic economic credibility increasingly important.
Countries with stronger reserves, improving external balances and credible monetary frameworks may have greater capacity to absorb global volatility.
Those with large refinancing needs, persistent inflation or fragile currencies may face a more difficult adjustment.
Nigeria’s recent improvement in reserves and inflation therefore matters. But the real test will be whether those gains are durable enough to withstand another period of strong-dollar conditions.
What Nigerian businesses should be watching
The next phase of the global rate cycle puts four variables firmly on the Nigerian corporate agenda: the dollar, oil, global bond yields and domestic inflation.
The dollar affects the naira cost of imported inputs and foreign-currency liabilities.
Oil determines a major share of Nigeria’s foreign-exchange earnings.
Global bond yields influence the cost of international capital.
And domestic inflation determines how much of the external shock can be absorbed before consumers and businesses feel another squeeze.
That is why Green’s advice that investors should treat every meeting between now and December as a live event has relevance beyond financial markets.
The precise timing of the Fed’s next move remains uncertain.
But businesses that assume the era of steadily cheaper global money is returning could find themselves exposed if that assumption proves wrong.
For companies, the practical question is increasingly straightforward: how much of the balance sheet is sensitive to the dollar, imported costs and refinancing rates?
For investors, it is equally important to understand duration and currency exposure.
A new global money map
The deeper significance of the Fed hike and BoE hold is that major central banks are no longer necessarily moving in the same direction at the same time.
That fragmentation matters for Africa because global financial markets remain interconnected.
A higher US rate can support the dollar. A stronger dollar can affect emerging-market currencies.
Currency movements can feed inflation. Inflation can constrain domestic monetary policy.
And higher interest rates can ultimately affect investment, employment and economic growth.
The chain from Washington to Abuja, and Lagos, Nigeria’s economic capital, is therefore much longer than a central-bank statement.
For Nigeria, the picture contains both protection and pressure. Higher oil prices can strengthen external earnings. Improving reserves and moderating inflation provide buffers. But stronger global yields and a firmer dollar can raise the hurdle rate for capital, increase the cost of foreign-currency obligations and complicate the disinflation process.
Green’s prediction of another Fed hike in December may prove right or wrong. The Federal Reserve will ultimately respond to the data available to it.
The bigger issue for African markets is that the global financial system has entered a period in which the direction of US monetary policy cannot be treated as background noise.
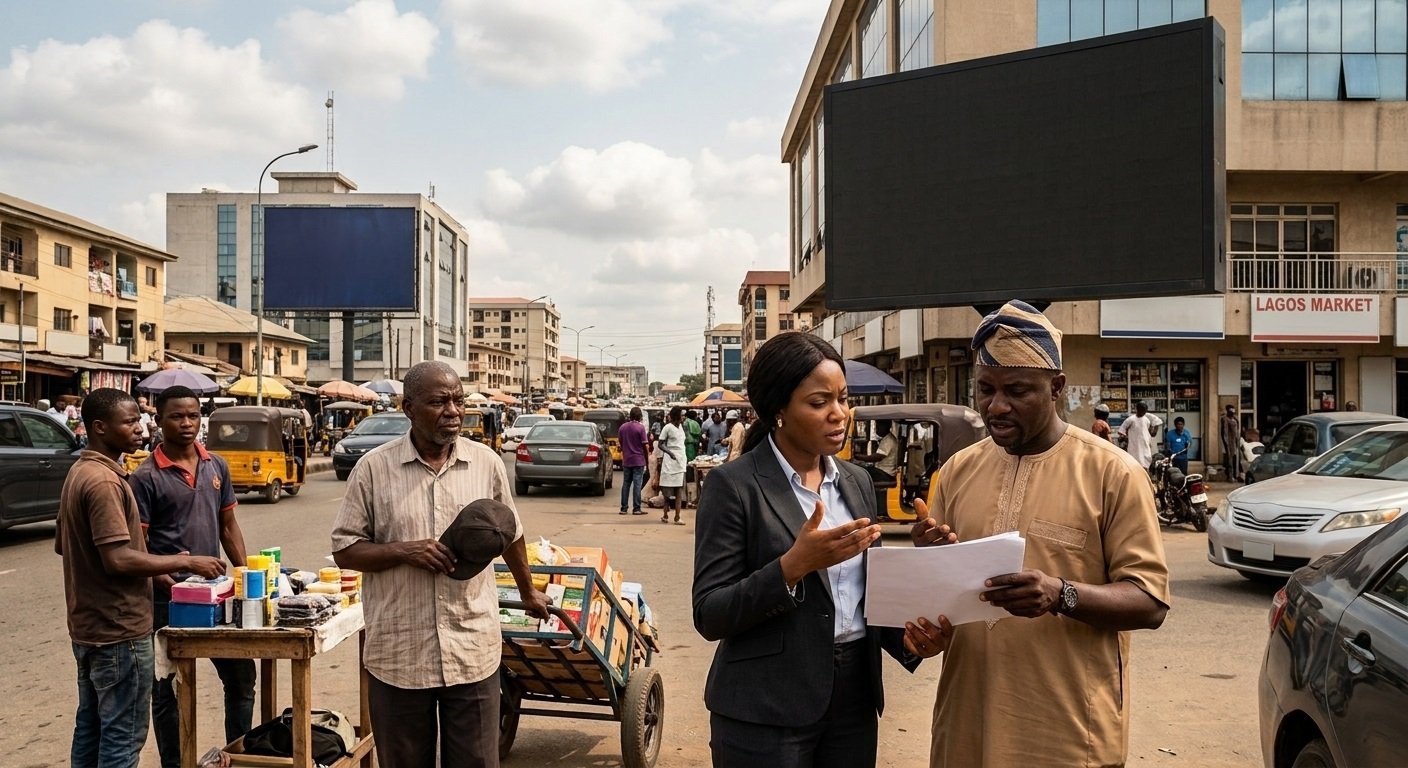
For Nigeria, the price of money in Washington is increasingly becoming part of the price of doing business in Lagos.