Business A.M
No Result
View All Result
Saturday, October 17, 2026
  • Login
  • Technology
  • Finance
  • Comments
  • Companies
  • Commodities
  • ONLINE & DIGITAL CONTENT PACKAGE
Subscribe
Business A.M
  • Technology
  • Finance
  • Comments
  • Companies
  • Commodities
  • ONLINE & DIGITAL CONTENT PACKAGE
No Result
View All Result
Business A.M
No Result
View All Result
Home Project Syndicate by business a.m.

Raising Interest Rates Won’t Stabilize African Inflation

by Business a.m.
June 14, 2026
in Project Syndicate by business a.m.
Inflation

CAMBRIDGE—African economies began this year facing no shortage of challenges, including lower global demand for their goods and services, unpredictable tariffs and other trade barriers, post-pandemic debt overhangs, structural unemployment, and large net financial outflows. Then the United States and Israel launched their war on Iran, throwing the Middle East into turmoil, halting traffic through the Strait of Hormuz, and compounding inflationary pressures. Now, inflation has reached double-digit rates in some African countries. But the traditional monetary-policy prescription—higher interest rates—will not work to contain it, and might even make matters worse.

To be sure, the International Monetary Fund has recommended monetary tightening, citing high public-debt levels, the risk of “procyclical spending surges” in oil-exporting economies, and the danger of overheating elsewhere. But this advice is analytically unsound, empirically flawed, and strategically dangerous. In fact, monetary tightening would amount to a demand-side remedy for a supply-side pathology.

Africa’s public debt did not arise from consumption. In most countries, fiscal and external deficits do not finance subsidies or excessive recurrent expenditure, but rather critical infrastructure needs and indispensable public services, such as hospitals and schools. These are assets with economic lives of 50 years or more, and productivity multipliers that standard—and short-sighted—debt-sustainability models underestimate.

Above-average growth in countries like Djibouti, Egypt, Guinea, Niger, Rwanda, Ethiopia, Morocco, Ivory Coast, and Tanzania reflects a supply-side expansion—in services, construction, and agriculture—not an unsustainable credit-fueled demand boom. Concerns about “overheating” are thus similarly misguided.

An economy overheats when demand for goods and services significantly outpaces the economy’s ability to supply them, and prices for labor and capital rise, generating demand-pull inflation, which interest-rate hikes can then dampen. But this framework applies in advanced economies with well-functioning labor markets, flexible wages, a capital stock operating near capacity, inflation expectations anchored by a credible central bank, and effective monetary-policy transmission mechanisms. None of these conditions holds for African economies.

Africa’s labor force is predominantly employed in subsistence and smallholder agriculture, the informal economy, and low-productivity services. Because agricultural labor markets are segmented, seasonal, and largely non-monetary in their clearing mechanisms, these sectors are not subject to the wage-setting dynamics that drive demand-pull inflation in industrialized economies. Wage pressure in the formal sector, which accounts for a small share of total employment, does not fuel economy-wide inflation.

Rising inflation in Africa is predominantly supply-side, cost-push, and structural in nature. As the IMF itself recognizes, it is driven by events beyond Africa’s control, which have raised the prices of goods African countries must buy from abroad, including fuel products, medicines, fertilizers, and food.

Standard macroeconomic theory holds that interest-rate increases work by raising borrowing costs (reducing investment and consumption, thereby cooling demand), tightening credit conditions (compressing spending), and strengthening the exchange rate (attracting capital inflows and lowering the cost of imports). In Africa today, none of these channels is particularly effective.

Start with borrowing costs. Higher interest rates cannot lower fuel or fertilizer prices, let alone resolve the conflict in the Middle East; they will have little impact on the informal urban sector and rural agriculture, which largely operate outside the formal banking system. This includes the smallholder farms providing the food that affects headline consumer price indices, and the informal food traders who set market prices for most African households.

What higher interest rates would do is raise the cost of credit for the small, formal, investable, growth-generating segments of the economy. This would undermine investment—including in critical sectors like energy generation and agro-processing—reducing productive capacity at precisely the moment when supply constraints are generating inflationary pressures.

The exchange-rate channel has some potential in the fight against inflation. But Africa’s capital accounts are often partly managed, and capital inflows arrive primarily in the form of foreign direct investment, not interest-rate-sensitive hot money. Moreover, domestic currency movements are determined more by structural trade deficits and global dollar dynamics than by marginal increases in central-bank rates.

A better strategy than monetary tightening would focus on accelerating the structural transformation that the continent badly needs, by channeling finance into productive and employment-creating industries.

To this end, African countries should establish or strengthen national development banks to provide long-term, below-market financing for strategic sectors and crowd in private investment. They should also use targeted credit allocation and refinancing facilities to direct lending toward priority sectors and mobilize domestic savings at scale through public-savings vehicles, sovereign funds, or development-finance institutions. Strict performance conditions and full transparency requirements should be attached to subsidized credit.

Export-credit institutions are also essential, with concessional finance and subsidies tied to measurable performance metrics, such as export targets, to instill discipline and prevent the financial system from succumbing to political patronage. As their economies mature, African countries should gradually recalibrate their financial toolkits, shifting from debt-heavy directed infrastructure credit to venture capital, equity participation, innovation finance, and regulatory sandboxes.

No economy has achieved structural transformation using textbook inflation-targeting and interest rates. Instead, success has depended on financial arrangements that solved coordination failures, financed long-term investment, and accelerated industrial upgrading. That approach, together with the diversification of food-production and energy systems, would go a long way toward strengthening Africa’s sovereignty, stability, and prosperity.

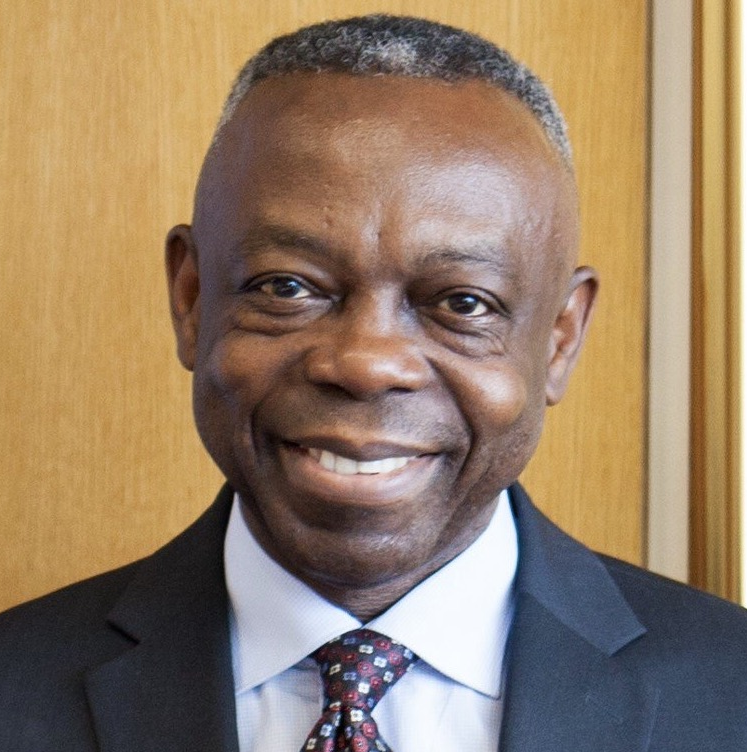
Célestin Monga, a former managing director at the United Nations Industrial Development Organization and a former senior economic adviser at the World Bank, teaches public policy and economics at Harvard Kennedy School. He is a former vice president and chief economist at the African Development Bank Group. He is the co-editor, (with Justin Yifu Lin) of The Oxford Handbook of Structural Transformation (Oxford University Press, 2019) and the co-author (with Justin Yifu Lin) of Beating the Odds: Jump-Starting Developing Countries (Princeton University Press, 2017).

Copyright: Project Syndicate, 2026.
www.project-syndicate.org

Business a.m.
Business a.m.
Previous Post

Domestic competence as Africa’s most important development strategy

Next Post

6G rollout risks repeating 5G’s commercial struggles, report warns 

Next Post
6G rollout risks repeating 5G’s commercial struggles, report warns 

6G rollout risks repeating 5G’s commercial struggles, report warns 

  • Trending
  • Comments
  • Latest

How UNESCO got it wrong in Africa

May 30, 2017

CBN to issue N1.5bn loan for youth led agric expansion in Plateau

July 29, 2025
MMA2 enters new commercial era after 20-year concession dispute

MMA2 enters new commercial era after 20-year concession dispute

August 28, 2026
NGX taps tech advancements to drive N4.63tr capital growth in H1

Insurance-fuelled rally pushes NGX to record high

August 8, 2025

6 MLB teams that could use upgrades at the trade deadline

Top NFL Draft picks react to their Madden NFL 16 ratings

Paul Pierce said there was ‘no way’ he could play for Lakers

Arian Foster agrees to buy books for a fan after he asked on Twitter

Rivers, China's CNCECC sign deal for $3.5bn methanol, fertiliser plant

Rivers, China’s CNCECC sign deal for $3.5bn methanol, fertiliser plant

October 17, 2026
Methane rules spread across 67% of global production as Nigeria faces compliance test 

Methane rules spread across 67% of global production as Nigeria faces compliance test 

October 17, 2026
Onafriq, a pan-African payments company, is set to discontinue its Baxi agent banking business in Nigeria after five years, citing naira depreciation, rising operating costs and intensifying competition that have weakened the segment’s profitability. The planned shutdown will affect the agent banking operations conducted through Baxi under Onafriq Nigeria Payments Limited. However, the decision does not signal the company’s withdrawal from Nigeria, as it intends to retain its cross-border payments network and card issuing services in the country. In a statement, Onafriq said changes in Nigeria’s operating environment since 2024 had significantly altered the economics of its offline agent banking business, making the existing model unsustainable. The move marks a strategic shift for the company, which entered Nigeria’s agent banking market to expand access to financial services through a network of agents providing transaction services outside traditional bank branches. Onafriq attributed the decision to a combination of macroeconomic pressures and structural changes in the country’s payments industry. According to the company, naira depreciation and inflation have affected transaction volumes, increased operating expenses and undermined the sustainability of its agent banking operations. The growing adoption of instant account-to-account transfers has also changed the mix of transactions handled by agents, while heightened competition among payment service providers has put further pressure on margins. These developments have made it increasingly difficult for the business to remain viable under its existing operating structure, prompting the company to reassess its long-term strategy. Dare Okoudjou, founder and chief executive officer of Onafriq, said the decision to close the business was difficult, particularly given the efforts of employees, agents and business partners who helped build the Baxi network. “We entered Nigeria with conviction and commitment, but did not achieve the outcome we set out for. Closing this business was a difficult decision to arrive at, one that affects colleagues, agents, and business partners across Nigeria who poured their hearts and soul into building out the Baxi network,” Okoudjou said. Despite the closure, he reaffirmed the company’s commitment to the Nigerian market, noting that the group would continue to serve customers through its payments network and card issuing operations. Onafriq entered Nigeria’s agent banking market in 2021 through the acquisition of Baxi, also known as Capricorn Digital Limited. The company said it continued investing in the business through 2023, with efforts focused on expanding and strengthening its agent network. However, a subsequent review of the business’s long-term prospects and financial sustainability led to the decision to wind down the operation. As part of the transition, Onafriq said agents onboarded through the Baxi platform had been moved to another principal bank, a step intended to facilitate continuity for the affected agents. The company has also directed agents to transfer their funds to their preferred principal bank within 30 days, adding that its teams would provide support throughout the transition process. Employees whose roles are linked to the agent banking business will also be consulted and supported during the wind-down, with Onafriq pledging to treat affected workers fairly.

Onafriq winds down Baxi as Nigeria’s agent banking economics worsen

October 17, 2026
LCFE links petroleum trading to capital market in pricing transparency drive

LCFE links petroleum trading to capital market in pricing transparency drive

October 17, 2026

Popular News

  • How UNESCO got it wrong in Africa

    0 shares
    Share 0 Tweet 0
  • CBN to issue N1.5bn loan for youth led agric expansion in Plateau

    0 shares
    Share 0 Tweet 0
  • MMA2 enters new commercial era after 20-year concession dispute

    0 shares
    Share 0 Tweet 0
  • Insurance-fuelled rally pushes NGX to record high

    0 shares
    Share 0 Tweet 0
  • Glo, Dangote, Airtel, 7 others prequalified to bid for 9Mobile acquisition

    0 shares
    Share 0 Tweet 0
Currently Playing

CNN on Nigeria Aviation

CNN on Nigeria Aviation

Business AM TV

Edeme Kelikume Interview With Business AM TV

Business AM TV

Business A M 2021 Mutual Funds Outlook And Award Promo Video

Business AM TV

Recent News

Rivers, China's CNCECC sign deal for $3.5bn methanol, fertiliser plant

Rivers, China’s CNCECC sign deal for $3.5bn methanol, fertiliser plant

October 17, 2026
Methane rules spread across 67% of global production as Nigeria faces compliance test 

Methane rules spread across 67% of global production as Nigeria faces compliance test 

October 17, 2026

Categories

  • Frontpage
  • Analyst Insight
  • Business AM TV
  • Comments
  • Commodities
  • Finance
  • Markets
  • Technology
  • The Business Traveller & Hospitality
  • World Business & Economy

Site Navigation

  • Home
  • About Us
  • Contact Us
  • Privacy & Policy
Business A.M

BusinessAMLive (businessamlive.com) is a leading online business news and information platform focused on providing timely, insightful and comprehensive coverage of economic, financial, and business developments in Nigeria, Africa and around the world.

© 2026 Business A.M

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • Technology
  • Finance
  • Comments
  • Companies
  • Commodities
  • ONLINE & DIGITAL CONTENT PACKAGE

© 2026 Business A.M